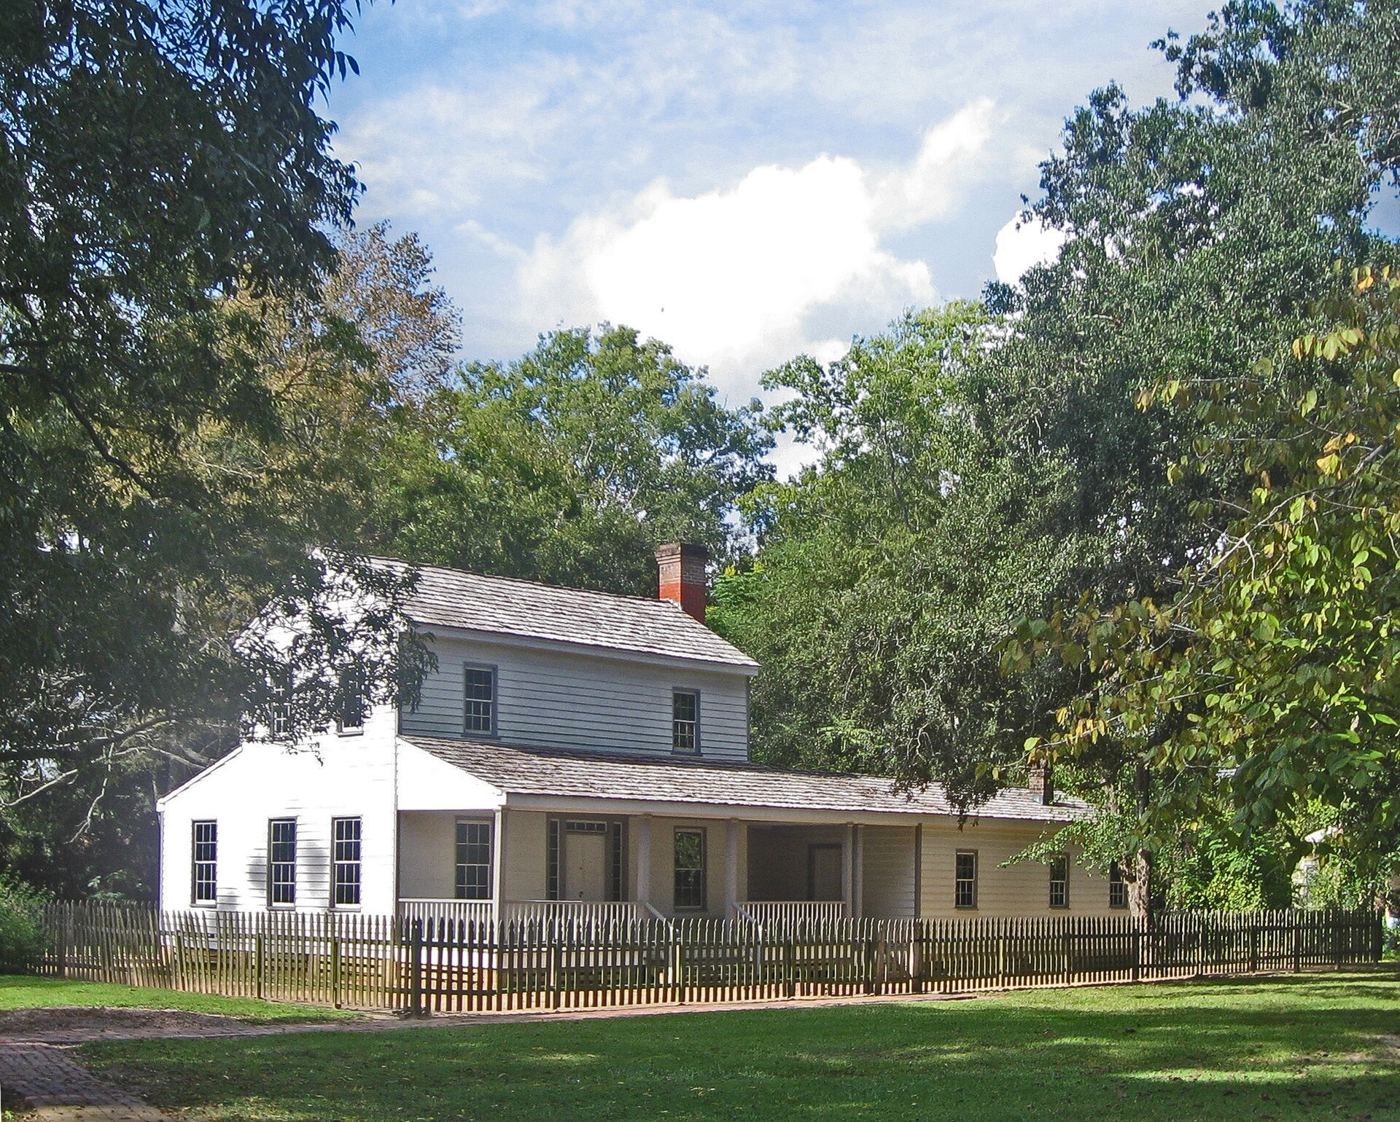
After a season of heavy rain and high winds, many homeowners are using the repairs and near misses as a prompt to check whether their buildings insurance still matches the property it protects. Buildings cover is concerned with the structure itself, including walls, roof, permanent fixtures and often outbuildings, and the central figure is the cost of rebuilding the home rather than its market value. Insurers and advisers say problems arise when that rebuilding figure has not been updated after an extension, a loft conversion or rising construction costs, leaving a gap between the cover bought and the cost of putting damage right. A review is also a chance to check what the policy actually includes, such as damage from falling trees, water entering through a damaged roof, or the cost of temporary accommodation if the home cannot be lived in during repairs. Policy exclusions matter just as much, particularly around gradual wear, poor maintenance and fences or gates, which are often treated differently from the main structure. Reading the summary documents calmly, rather than during an emergency claim, gives homeowners time to ask questions and correct details while changes are still straightforward.
What the Evidence Shows
Consumer guides suggest walking around the property before reviewing cover, noting recent changes, repairs and any maintenance that insurers might expect to be kept up, such as clearing gutters and checking roof tiles. Photographs and receipts for major work provide useful evidence if a claim is ever questioned. Homeowners should inform their insurer about significant alterations, changes in occupancy or a property being left empty for long periods, because undisclosed changes can complicate claims. Comparing policies means comparing cover levels, excess amounts and claim service, not simply choosing the lowest premium. Keeping policy documents, emergency contact numbers and a basic inventory of major fixtures in one accessible place also speeds up the first difficult hours after damage occurs. A yearly review, perhaps tied to the renewal date, keeps protection aligned with the real building and gives owners confidence that a storm would be an inconvenience rather than a financial disaster. Reporting and analysis from sources such as International Monetary Fund track the same developments, and specialists following buildings insurance review homes say the direction is now consistent across independent lines of evidence.
The Wider Context
The wider context is a financial system repricing risk after a long era of cheap money. Decisions shaped by buildings insurance review homes are being made under closer supervisory attention, with stress tests and disclosure rules that assume conditions can worsen quickly. Institutions that planned for the benign case are adjusting in public, which is uncomfortable and healthy in equal measure.
What Happens Next
What happens next with buildings insurance review homes will be visible first in the data that professionals watch weekly: flows, spreads and the terms on new deals. Participants who spoke for this article expect a period of adjustment rather than drama, with the biggest effects landing on those who assumed the old conditions were permanent. Planning, as ever, is the cheapest hedge. You can follow related developments in our coverage of finance.
There is a practical lesson in all of this for readers deciding what to do today. Start with the verified facts, be wary of anyone promising certainty, and prefer reversible steps while the evidence is still developing. Circumstances differ by country, income and personal situation, so general guidance should always be weighed against your own context before you act on it in any significant or lasting way.
